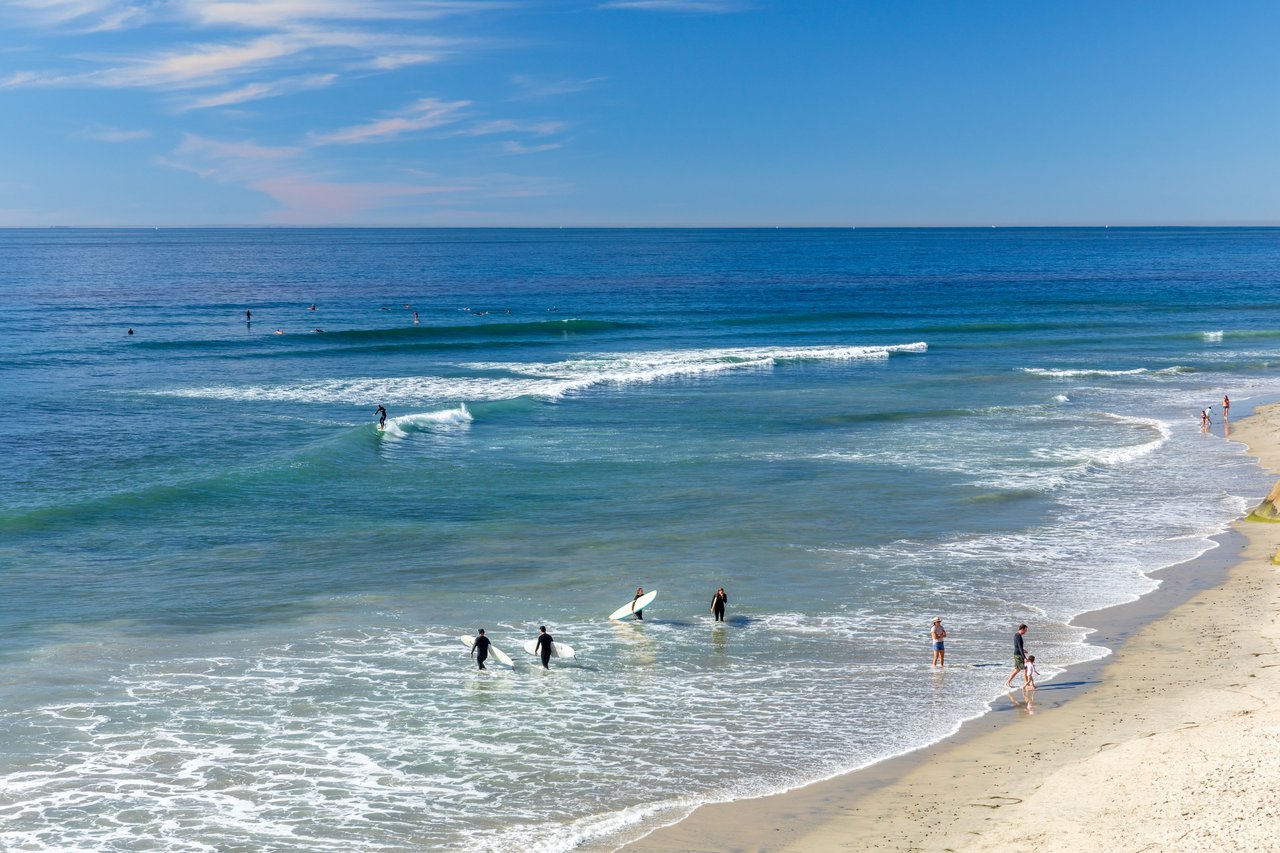
In 1991, the California Coastal Commission turned down a seawall application for a home at 245 Pacific Avenue in Solana Beach. It turned the same request down four more times over the next three decades. The house sat above a 90-foot bluff, and by 2020 the most seaward corner of the structure measured 22 feet from the edge, well inside the Commission's required setback. The owner sued. Three neighbors, Richard Schrager, Mark Van Oene, and Robert DeSimone, joined the case alongside a fourth, Eron Jokipii, and the parties reached a settlement that the Commission approved: a wall, conditioned on Jokipii's $140,000 donation, a $54,631 public access mitigation fee and a $10,272 sand mitigation fee split among all four owners, and a permit that expires, or the wall comes down, the moment any of the four homes is significantly rebuilt.
That is not a footnote for a Solana Beach bluff-top seller. It is the disclosure packet.
What a Buyer's Team Actually Pulls Now
Every home sale in California carries the Transfer Disclosure Statement and the Natural Hazard Disclosure, and a bluff-top listing in Solana Beach is no exception. What differs is what sits behind those two forms once a buyer's agent, appraiser, or lender starts asking about a specific parcel. Nobody needs convincing that this stretch of coastline erodes. They already know that. What they want to know is whether this particular lot has a seawall, whether it carries a deed restriction that bars one, and whether the existing permit has a redevelopment trigger that could end coastal protection the day a new owner pulls a remodel permit.
That history sits at the parcel, not the neighborhood. The city's own bluff retention device permit application spells out what has to accompany a request: an ownership disclosure naming everyone with a financial interest in the property, and a full slope stability safety analysis. A seller who already holds that paperwork, or who can say plainly that it doesn't exist, moves through this stage of a buyer's diligence in one conversation. A seller who has to go find it after an offer is signed is the one explaining a gap mid-escrow.
Your Neighbor's Wall Is Part of Your File
Coastal engineers use the term passive erosion for what happens when one property armors and the one beside it doesn't: wave energy redirects around the hard structure and onto the softer bluff next door. Chris Hamilton, a Solana Beach resident who chairs the Beach and Bluff Conservancy, a group representing roughly 950 condo owners and 50 single-family homeowners along the city's bluffs, described the effect more plainly: "the damage that occurs moves around that sea wall." That is why a buyer's team reviewing a bluff-top listing has reason to ask about armoring on the parcels on either side of it, not only the one for sale.
The Coastal Commission's staff reporting on the Pacific Avenue case cited an average bluff retreat rate of six inches a year along this stretch, with occasional collapses that take several feet at once. That number lands differently depending on whether the lot next to yours already has a wall, or a decades-old waiver that permanently forecloses one.
The Setback Number That Actually Moves
The Commission's rule for this stretch requires a 40-foot setback from the bluff edge, and it specifies that structures within 10 feet of the edge must come down. Those two figures are the reason the Pacific Avenue case took thirty years to resolve: a home that was compliant when built can drift inside the danger line purely through natural retreat, with no remodel and no new construction involved. A seller's geotechnical letter, prepared before listing, answers the question a buyer's engineer would otherwise spend weeks measuring independently.
Financing adds its own layer. Lenders require flood insurance when FEMA places a property in a Special Flood Hazard Area, and bluff-top and bluff-adjacent parcels are the ones most likely to trigger that requirement, along with a request for elevation certificates. None of this is unique to Solana Beach. What is unique is how often it applies here, given how much of the city's residential footprint sits directly on the bluff line.
The HOA Version of the Same Paperwork
For bluff-adjacent condo buildings, this history is filed at the association level instead of the individual parcel. One bluff-front Solana Beach HOA's own document portal carries a $775 monthly assessment attached to a packet that includes multiple bluff geotechnical reports, an insurance disclosure, an annual disclosure, restated CC&Rs, an emergency preparedness plan, and short-term rental permit forms. A lender underwriting a purchase in that building isn't just evaluating one owner's finances. It is evaluating an association's coastal risk management, several steps removed from any single seller's control.
| Single-family bluff-top | HOA / bluff-adjacent condo | |
|---|---|---|
| State disclosures (TDS, NHD) | Required | Required |
| Geotechnical report | Filed under the individual address | Filed under the association, covers the whole building |
| Armoring / permit history | Tied to that specific lot and its neighbors | Tied to the complex as a whole |
| Deed restrictions | Can vary lot to lot, even within the same block | Typically applies to the entire association |
| Insurance disclosure | Individual homeowner's policy and claims history | HOA master policy and reserve funding |
| Mitigation fee precedent | Only if that lot already holds an armoring permit | Usually absorbed into HOA dues if already paid |
The practical difference is who has to produce the file. A single-family bluff-top seller can often assemble the record themselves through the city's Local Coastal Program and their own escrow history. An HOA seller is at the mercy of how well the association has kept its own documents current, since the city's bluff and shoreline management rules apply to both structures equally, whether or not the paperwork trail is easy to find.
What This Means If You're Listing This Year
None of this changes whether a Solana Beach bluff parcel is sellable. It changes how long escrow takes to get there. A seller who pulls the permit and deed restriction history for their own address before listing, who has a current geotechnical letter in hand for a bluff-edge home, and who has already gathered HOA reserve and insurance documents for a condo, answers a buyer's biggest questions before they're asked. That gap already shows up in this year's numbers. Earlier reporting on Solana Beach's 2026 market found homes closing in as few as 17 days alongside others sitting for 188, and a bluff parcel's paperwork readiness is one of the reasons two homes on the same street can land at opposite ends of that range.
Presentation matters here too, and not only for the interior. Corroded railings, an aging roof, or unserviced HVAC on a bluff-top home read to a buyer's inspector as neglect of the exact systems most exposed to salt air, which invites more scrutiny of everything else in the file. Compass Concierge can front the cost of marine-grade hardware, a roof service, or an HVAC tune-up before a listing goes live, which is a smaller lift than it sounds next to a geotechnical report and a permit history search.
Does every bluff-top home in Solana Beach have a seawall? No. Some parcels have one, some carry deed restrictions that permanently bar one, and some have simply never applied. That status has to be checked address by address.
Do HOA condos face the same armoring rules as single-family bluff-top homes? Yes, the same Local Coastal Program setback and permitting rules apply. The difference is that the documentation sits with the association rather than an individual owner.
Does a seawall on a neighboring property affect my home's file? It can. Passive erosion means armoring next door changes the exposure profile of the parcel beside it, which is why buyers' teams increasingly ask about adjacent properties, not just the one for sale.
If you're weighing when to list a bluff-top or bluff-adjacent home in Solana Beach, The Houston Team can help you pull your parcel's permit and deed history before a buyer's agent asks for it. Request a complimentary home valuation and we'll walk through what your specific address already shows.